
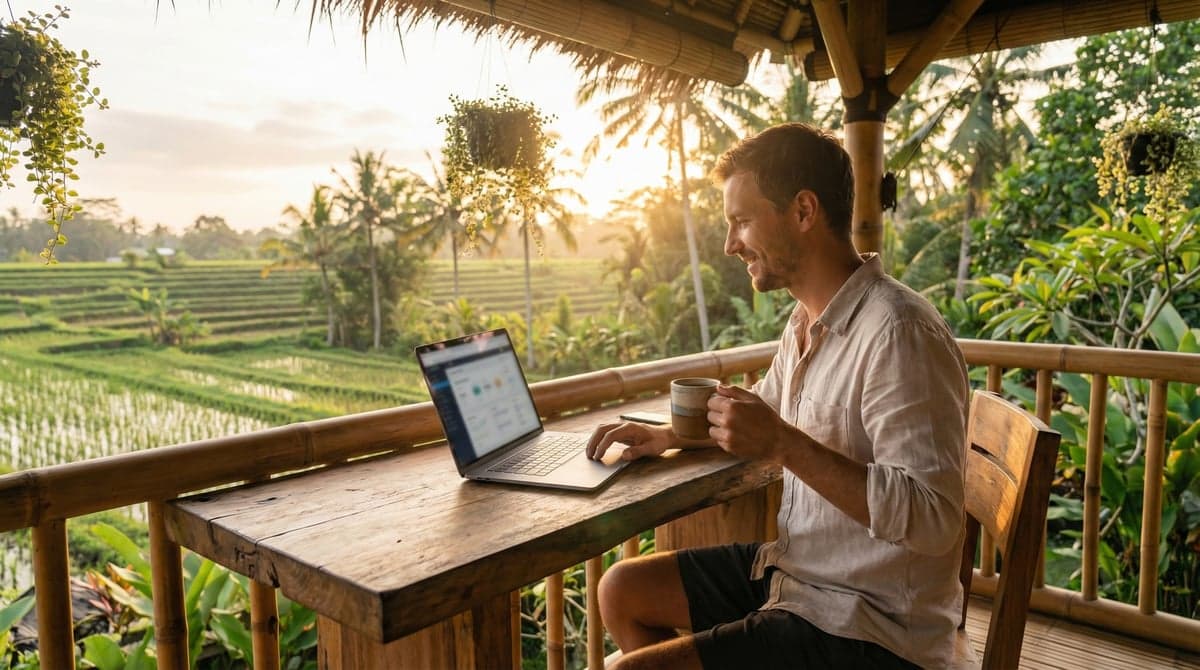
Indonesia 0% Tax on Foreign Income 2026: PMK 18/2021 Explained for Expats
Key Takeaways
TL;DR: Under PMK 18/2021, new Indonesian tax residents pay 0% on foreign-sourced income for the first 4 years. Conditions: income must originate outside Indonesia, not remitted as taxable Indonesian income, and you must meet the "new resident" definition. E33G Digital Nomad holders are NOT automatically exempt — tax residency status determines this, not visa type.
THE 30-SECOND BRIEF
Is this real? Yes. And it's legal.
- What: Indonesia taxes only Indonesian-sourced income (territorial system)
- Who benefits: Expats earning from foreign clients/employers
- The rule: PMK 18/2021 + UU HPP 2021
- Result: Foreign income = 0% Indonesian tax
- Risk level: LOW if structured correctly
THE FACTS
Since 2021, Indonesia operates a territorial tax system under PMK 18/2021. This means:
| Income Source | Taxed in Indonesia? |
|---|---|
| Work for Indonesian company | Yes |
| Clients in Indonesia | Yes |
| Foreign employer (no PE in Indonesia) | No |
| Foreign clients, work done remotely | No |
| Dividends from foreign stocks | No |
| Rental income from overseas property | No |
The official regulation: PMK No. 18/PMK.03/2021
Key distinction:
- Indonesian-sourced income = Taxed at normal rates (5-35%)
- Foreign-sourced income = Not brought into Indonesia = 0% tax
If you're a tax resident of Indonesia (183+ days/year) but earn income from:
- A foreign company with no presence in Indonesia
- Foreign clients who pay you offshore
- Investments held outside Indonesia
That income is not subject to Indonesian income tax, as long as it stays outside Indonesia for at least 3 years (for individuals) or is used for specific purposes if remitted earlier.
WHO QUALIFIES?
You can benefit if you:
| Condition | Required? |
|---|---|
| Tax resident of Indonesia (183+ days) | Yes |
| Have NPWP (tax number) | Yes |
| Income is foreign-sourced | Yes |
| Income not yet remitted to Indonesia | Recommended |
| Income from employer with no Indonesian PE | Yes |
You probably don't qualify if:
- Your employer has an office in Indonesia
- You invoice Indonesian clients
- You're paid through an Indonesian bank account
- Your work is performed IN Indonesia FOR Indonesian entities
THE BALI ZERO TAKE
What most expats get wrong:
The "0% tax on foreign income" isn't automatic. It requires:
- Proper structuring of your employment/freelance relationship
- Keeping income offshore (at least initially)
- Documentation proving the income source is foreign
- Compliance with NPWP and annual tax filings
The reality check:
Many digital nomads in Bali believe they're "tax free" because they earn in USD. Wrong. If you're here 183+ days, you're a tax resident. You MUST file an annual SPT.
The good news: Your foreign income may indeed be 0% taxed. But you need to:
- Have an NPWP
- File your SPT Tahunan every year
- Report your foreign income (even if not taxed)
Mistake 1: Not filing at all ("I'm not taxed, why file?")
- WRONG. Tax residents must file, even if liability is zero.
Mistake 2: Mixing Indonesian and foreign income
- If your foreign client also has Indonesian operations, it gets complicated.
Mistake 3: Assuming VOA/B211A means no tax residency
- Your visa type is irrelevant. 183 days = tax resident.
PRACTICAL EXAMPLE
Marco, Italian freelancer in Ubud:
- Lives in Bali 300 days/year
- Has B211A visa
- Works for 3 European clients
- Paid to Wise account (EUR)
- No Indonesian clients
Marco's tax situation:
- Tax resident? Yes (300 days)
- NPWP required? Yes
- Must file SPT? Yes
- Indonesian tax on European income? 0%
What Marco must do:
- Get NPWP (one-time)
- File SPT Tahunan by March 31 each year
- Report foreign income as "non-taxable"
- Keep bank statements as proof of foreign source
HOW TO SET THIS UP RIGHT
Step 1: Get Your NPWP
Even if your tax is zero, you need an NPWP. Guide here
Step 2: Structure Your Income Correctly
- Ensure clients pay to a foreign bank account
- Have contracts that clearly state foreign entity
- Avoid any Indonesian PE (permanent establishment)
Step 3: File Annually
- Deadline: March 31 for individuals
- Report all income (Indonesian + foreign)
- Apply territorial exemption for foreign income
Step 4: Keep Documentation
- Foreign contracts
- Bank statements showing offshore payments
- Proof that income stayed outside Indonesia (if applicable)
THE FINE PRINT
3-Year Holding Period (for some cases):
Under PMK 18/2021, if you want to remit foreign income to Indonesia tax-free, you may need to:
- Hold it offshore for 3 years, OR
- Invest it in qualifying Indonesian instruments
This applies mainly to investment income. Salary/freelance income has more flexibility.
What if I bring money to Indonesia?
If you remit within 3 years:
- May be taxed at normal rates
- Unless used for specific exempt purposes
Our advice: Consult a tax professional before moving large sums.
NEXT STEPS
- Check your situation - Are you truly earning from foreign sources?
- Get NPWP - Foreigners guide here
- Structure properly - Foreign contracts, foreign payments
- File correctly - Annual SPT with proper exemption claims
- Consult an expert - For complex cases
RESOURCES
- PMK 18/2021 - Official DJP link
- NPWP for Foreigners - Our guide
- Tax Residency Rules - 183-day rule explained
More in this series — Tax Residency & 183-day rule
Ask Zantara
AI-powered answers from our knowledge base
Category: tax-legal Priority: high Tags: PMK 18/2021, territorial tax, foreign income, expat tax Sources: PMK 18/2021, UU HPP 2021, DJP official guidance Last Updated: January 4, 2026
Topics
Bali Zero Editorial
Editorial Team
Questions about how this applies to your case?
Bali Zero handles visas, company setup, tax and property compliance in Indonesia. Ask us directly on WhatsApp.
Chat with Bali Zero on WhatsApp